

Financial engineering and mathematics at Duke (B.S.E. Risk, Data, and Financial Engineering, December 2026). I build statistical and computational models for markets and risk.
Now
- Capstone research on how macroeconomic shocks propagate through financial systems, advised by Dr. Mark Borsuk and Dr. Peng Sun
- Probability-distribution modules for Multivarious, Prof. Henri P. Gavin's open-source Python library for probability, optimization, and stochastic modeling
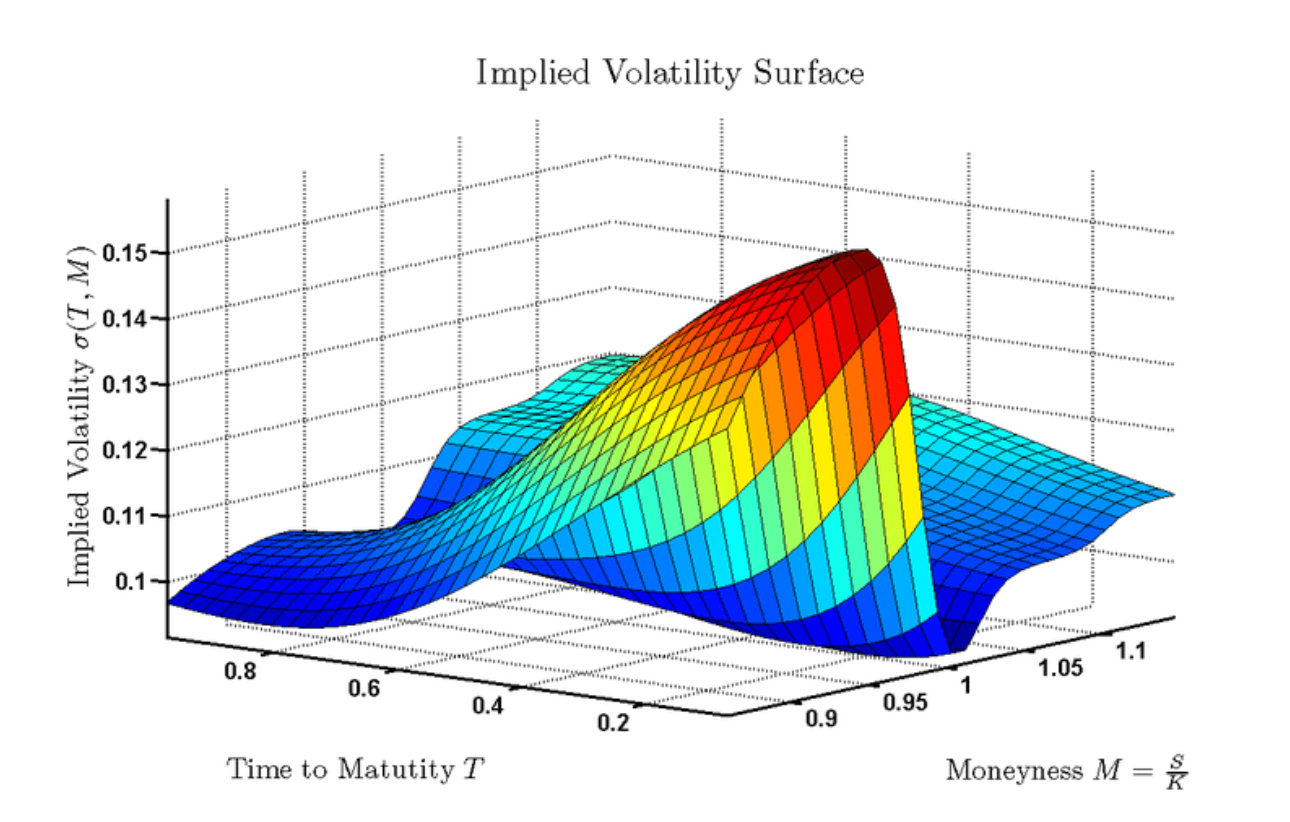
Modeling Market Geometry Implied volatility · PCA · QuantConnect · 2025 Fits daily implied-volatility surfaces, decomposes their changes into level, skew, and curvature, and trades that momentum with delta-neutral straddles and strangles. Paper · Repository |
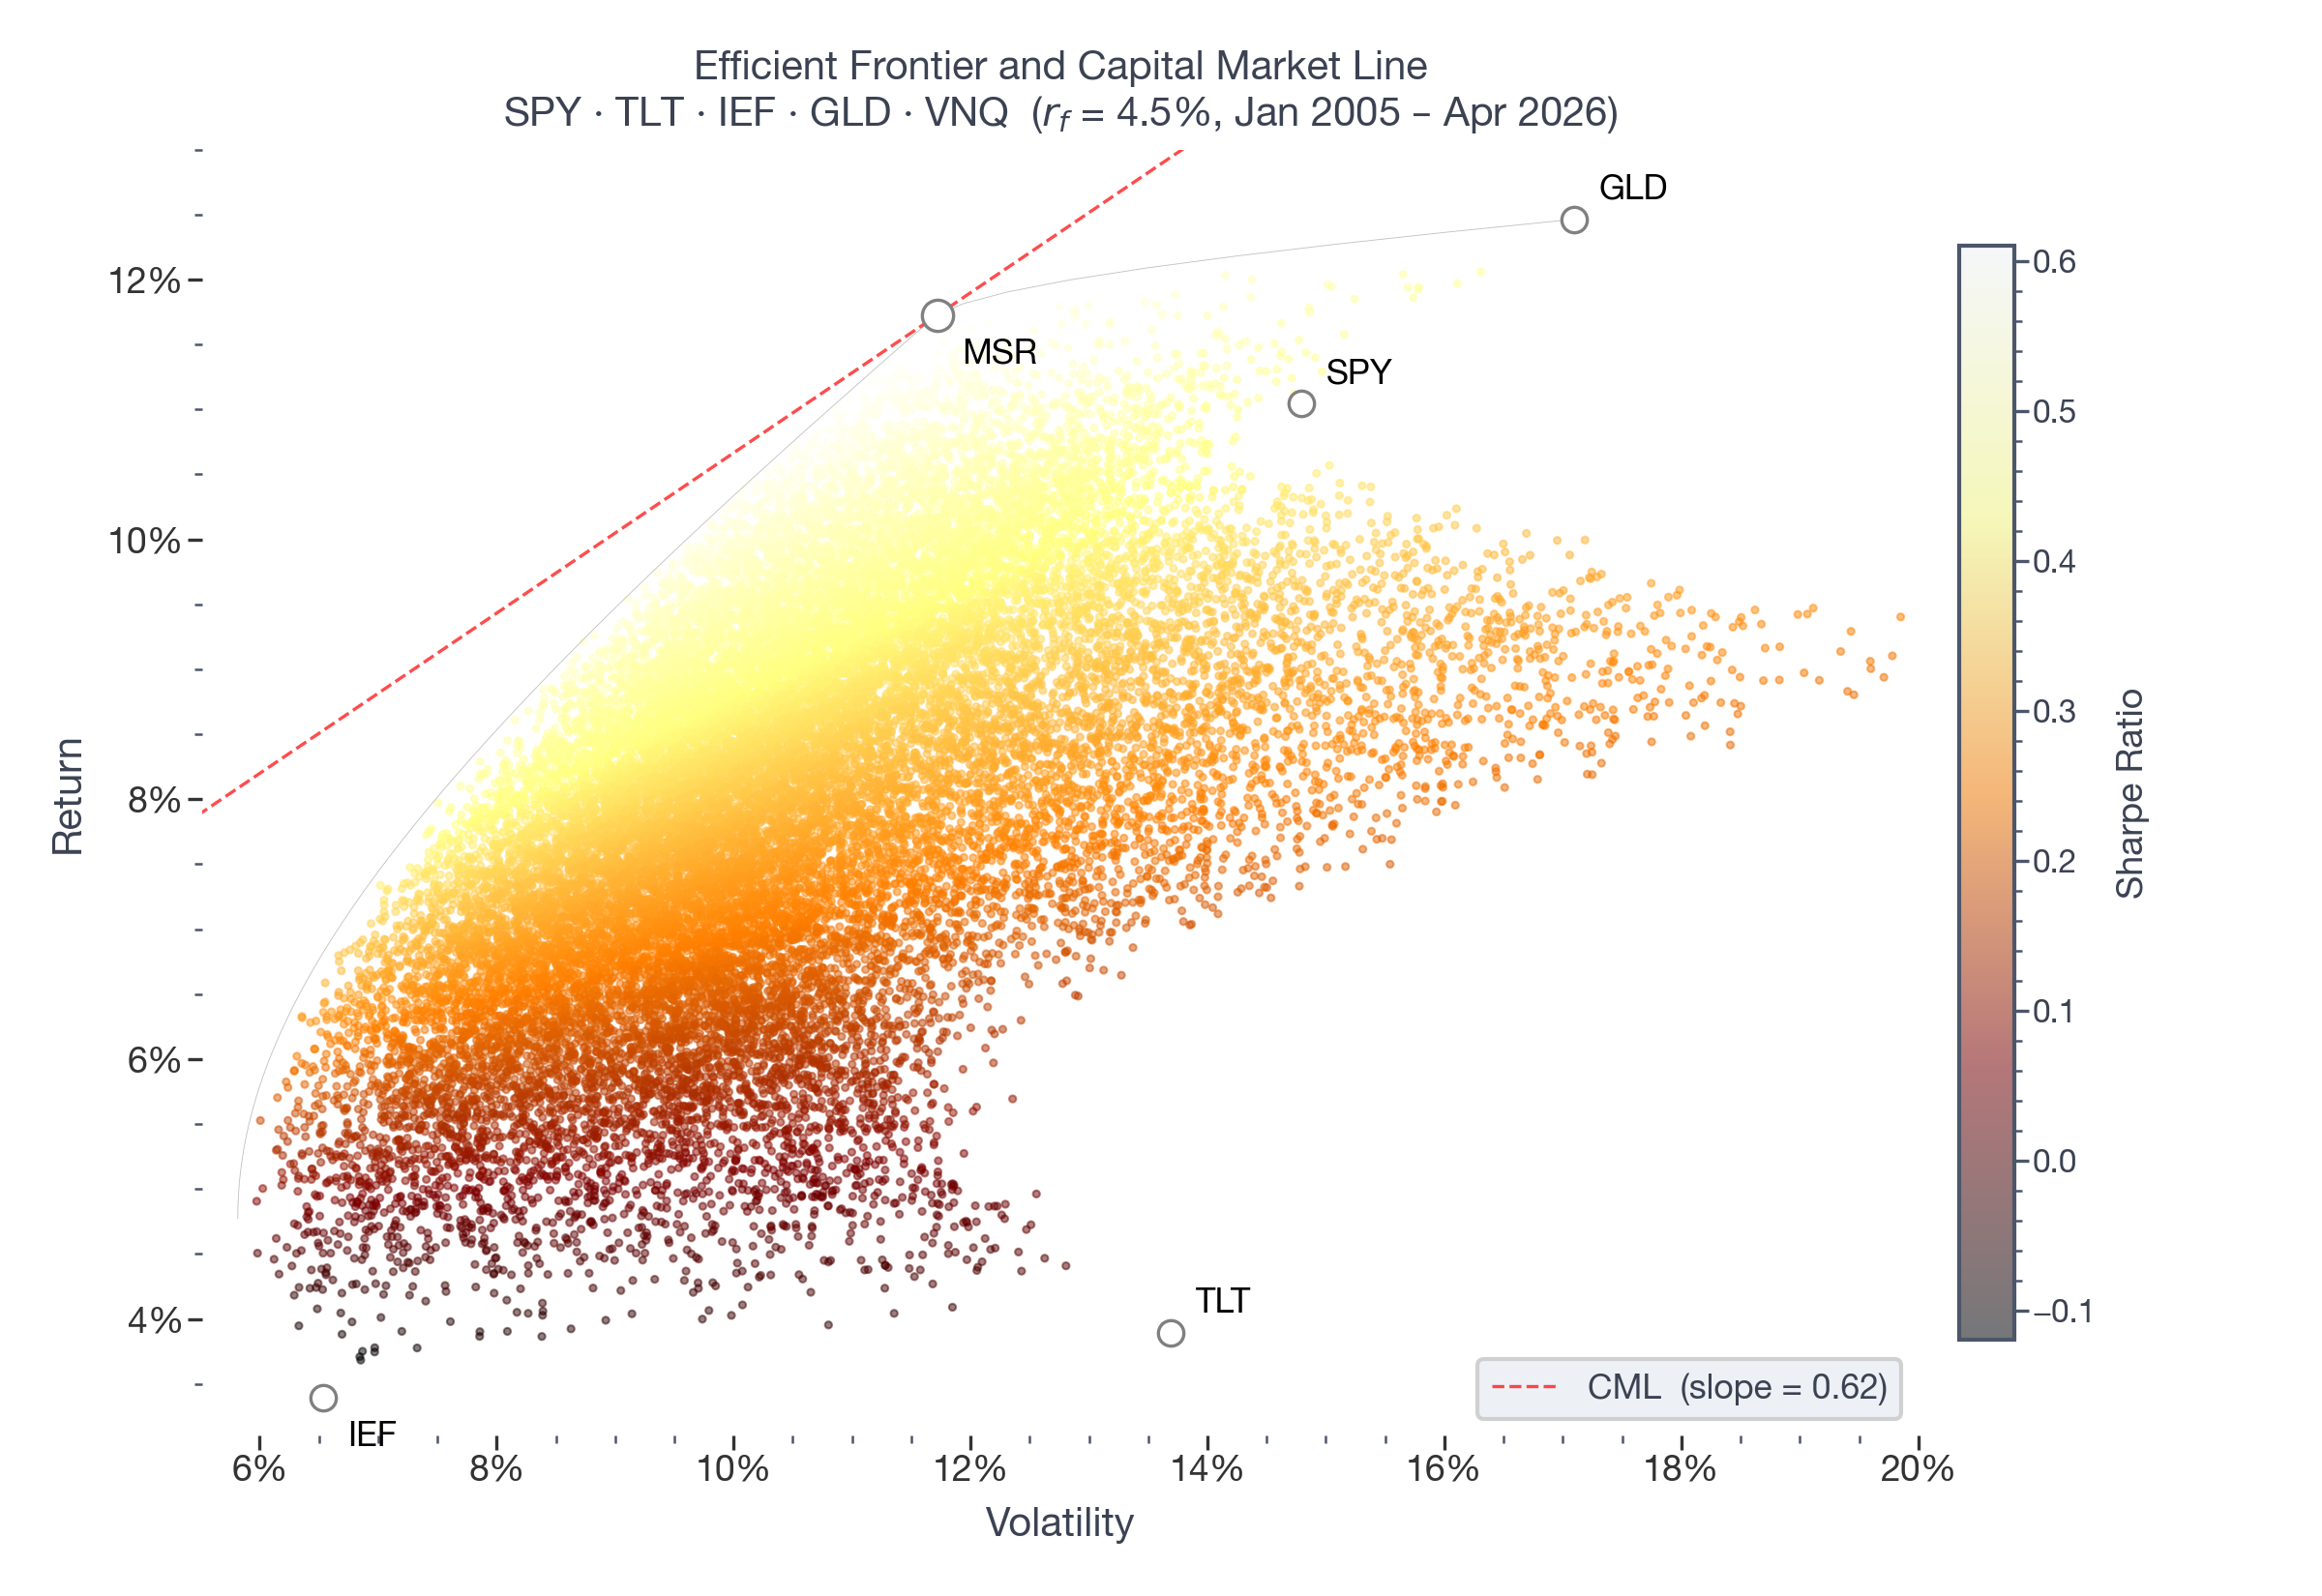
Modern Portfolio Optimization Approaches Mean-variance · Risk parity · QuantConnect · 2026 Tests mean-variance and risk parity over 18 years of walk-forward rebalancing on seven ETFs, and proposes a hybrid that caps each asset's share of portfolio risk. Paper · Repository |
| Project | Summary |
|---|---|
| Options Data and a Covered-Call Book | LSEG option data, an implied price surface, and a Reg T covered-call backtest, published as live sites |
| Water Supply Optimization | Fifty-year stochastic design of a drinking-water system under climate uncertainty |
| Quantitative Risk Management | Covariance repair, VaR and ES, risk parity, attribution, and option pricing in Python |
| Loan Default Prediction | A credit-risk pipeline built around an imbalanced dataset |
Tools: Python (NumPy, pandas, SciPy, scikit-learn, PyTorch), MATLAB, C++, Git, Bloomberg, LSEG